- The “New Generation Piggy Bank” turns social policy into investment capital for banks.

By
Vasilis Zografos
CEO of Vision Labs R&D Team,
PhD candidate in Information and Data Science,
BSc (Hons).CS, MBA.IB, MSc.DS, PhD.C.
[email protected]
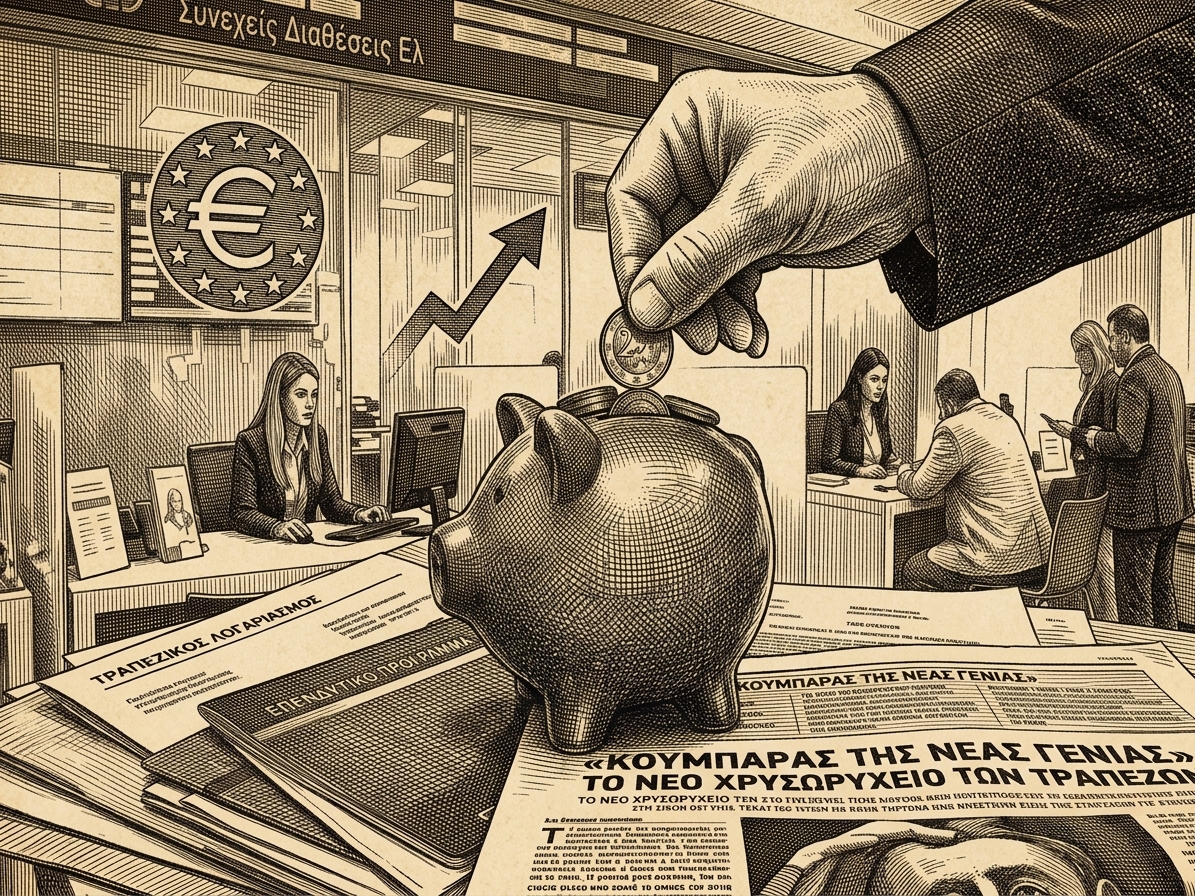
The “New Generation’s piggy bank”—the banks’ new gold mine.
The name “Piggy Bank for the Next Generation” possesses undeniable communicative intelligence and refers to family savings, parental care, security, and the creation of an initial capital for adulthood. State participation, private savings, multi-year commitment of funds, investment management, banking intermediation, and digital tracking compose a system with social, economic, and institutional ramifications much broader than those of a simple children’s account.
The phrasing “one euro from the family, one euro from the state” appears completely equal, but mathematical equality does not imply social equality. The family that is unable to save, due to the absorption of income by rent, energy, food, transportation, and raising children, loses the possibility of public assistance.
The child is integrated into a system of contribution, state matching, investment return, capital accumulation, and risk management. Social protection moves gradually from direct coverage of needs toward the creation of an investment asset for the future. The family that struggles today to pay the cost of living does not automatically acquire a greater ability to have children simply because the child may possess capital after 16 years.
Political language refers to savings, while the economic mechanism presupposes investment management. The higher hypothetical returns are accompanied by greater volatility and investment risk. No projection of future capital can be treated as a guaranteed return. At the same time, the nominal value of the amount at 18 is not equivalent to today’s purchasing power. Inflation will significantly erode the real value of the final capital, especially if net returns, after costs and commissions, remain low.
The new generation will create a multi-year, predictable, and state-co-financed flow of assets under management. An indirect, long-term fueling of the financial system with predictable private and public capital is created, with a time horizon reaching 16 years for an account opened at the age of two years. The stability of the flows allows long-term investment planning and drastically reduces the risk of sudden outflows.
The financial system also acquires a recurring income on top of a capital that grows year after year, with the completion of management, custody, participation, or transaction fees. They acquire maximum economic weight when applied for 16 years to hundreds of thousands of accounts. Full disclosure of charges, investment products, eligible managers, and actual net returns therefore constitutes an elementary condition of transparency.
Banks acquire a particularly significant strategic advantage of customer relationship with an entire generation, even before it acquires financial autonomy. The relationship in the future will expand to cards, loans, mortgages, investment, and insurance products. A corresponding cross-selling opportunity is created toward parents as well, during the operation of the program. Channelling part of the funds into Greek bonds, corporate issuances, or domestic investment products will strengthen the capital market and create additional turnover for financial intermediaries.
The multi-year commitment of funds implies a substantial loss of liquidity. A family may face an emergency long before the child reaches adulthood. The total exclusion of withdrawal possibility transforms savings discipline into economic entrapment. Equally serious remains the political risk of a 16-year commitment. Multiple governments, fiscal crises, and tax policy changes will intervene until the maturity of the first accounts. Maintaining state participation, the tax regime, and the protection of accumulated capital requires increased legislative guarantees.
The digital state constitutes the invisible but absolutely necessary mechanism of operation for the entire venture. The implementation of the program requires registry interoperability, automated certification of beneficiaries, anonymization of collected data, digital identification, electronic tracking of contributions, state participations, and returns, as well as advanced interfaces between the Public Sector and the financial sector. Requirements for cybersecurity, data minimization, strict access control, and prohibition of secondary use increase.
The “Piggy Bank for the Next Generation” will be judged by the distribution of the economic benefit during its long period of accumulation. Behind the promise of an adulthood capital, a multi-layered financial architecture is formed, where family income meets public funding, the banking system acquires long-term and predictable capital flows, managers potentially reap recurring fees, and the digital state establishes an economic information relationship with the citizen already from the first years of their life.
The social legitimization of the mechanism presupposes redistributive justice, financial transparency, strict supervision, zero tolerance for conflicts of interest, protection of informational self-determination, and full accountability for every euro of public money and every percentage point of management cost. Otherwise, the seemingly welfare policy risks transforming into a peculiar mechanism of socializing funding and privatizing yield, where the citizen contributes, the taxpayer co-finances, the child assumes the temporal and investment risk, and the financial ecosystem utilizes the capital for as long as it remains committed. The real evaluation of the measure will not take place at the moment the child opens their piggy bank at 18, but over the perpetuity of 16 years, during which some will manage its contents and the percentage of benefit that third parties have reaped.