–They are betting it won’t cope with the bureaucracy and will give up
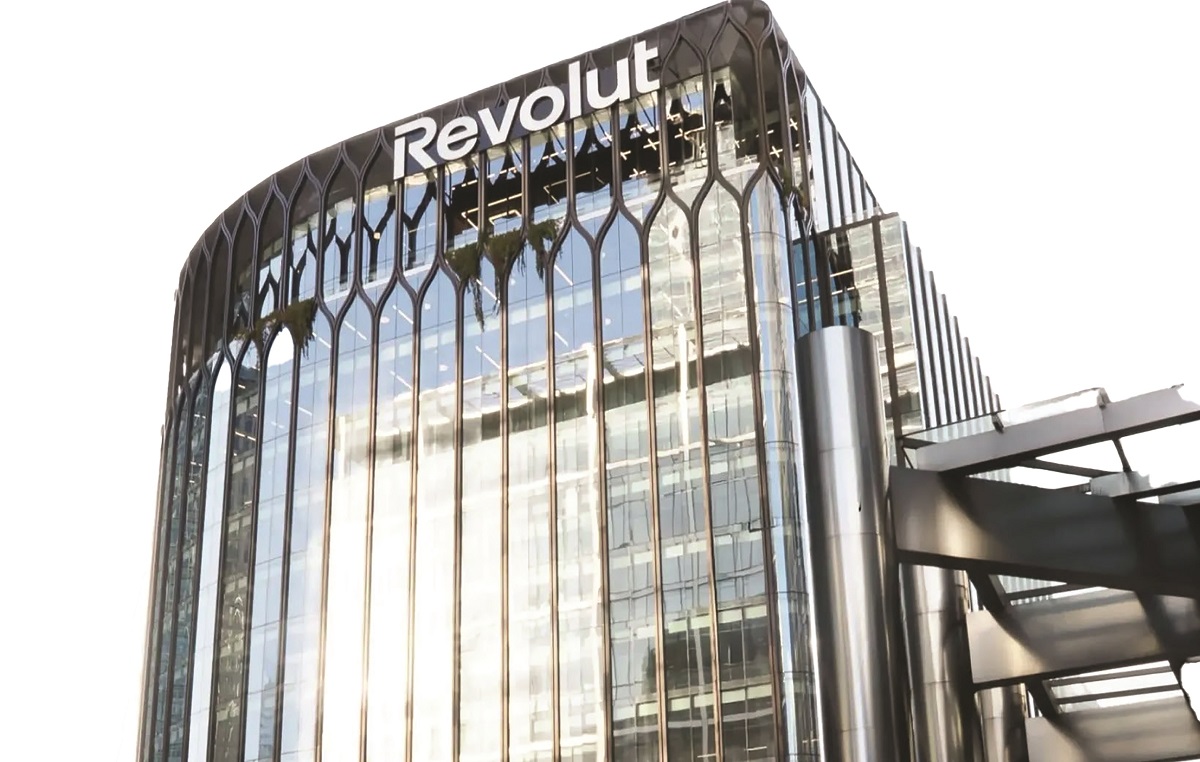
The Bank of Greece’s recent approval for Revolut to establish a branch in the country, combined with the imminent provision of Greek IBANs, is not just another news item. It marks the starting point of a tectonic shift in the domestic banking landscape.
The digital bank has chosen Greece as a strategic test market, with the clear goal of proving it can evolve into the average citizen’s primary bank—the place where their salary is directly deposited and their daily transactions are carried out.
To make this experiment succeed and establish itself in the market, the platform is prepared to invest vast sums and resources, thereby exerting immense pressure on the domestic banking system.
However, the foreign executives are likely unprepared for what awaits them in the next stage: a head-on collision with the “monster” of Greek bureaucracy.
This is precisely where domestic bankers are pinning their secret hopes. They are banking on the idea that labyrinthine procedures, the system’s structural inertia, and the Bank of Greece’s strict regulatory mazes will act as a powerful, invisible brake, stifling any trace of genuine innovation Revolut intends to implement.
This expectation of institutional inertia largely explains the arrogant attitude of Greek banks. They have shown utter disregard for the average consumer and their actual needs. Instead of improving their customers’ daily lives by offering competitive products, they busy themselves with grandiose announcements regarding new acquisitions and supposedly revolutionary AI integrations, merely creating a veneer of modernization for public relations purposes. The reality, however, is far more cynical—a fact clearly reflected in the question aptly posed recently by legal expert Leonidas Stamos in an article. The unspoken truth is that the staggering profitability of our four systemic banks—soaring to €4.7 billion in a country where seven out of ten depositors hold less than €1,000 in their accounts—does not stem from successful retail banking or innovative services.
It relies almost exclusively on managing, circulating, and capitalizing on the vast sums of state and European funds that are mandatorily channeled through them.
Revolut is now openly vying for the neglected average Greek customer. Whether its technological agility can overcome the quagmire of bureaucracy—upon which the domestic banking oligopoly relies to safeguard its privileges—is the great challenge that lies ahead.
TO PARON